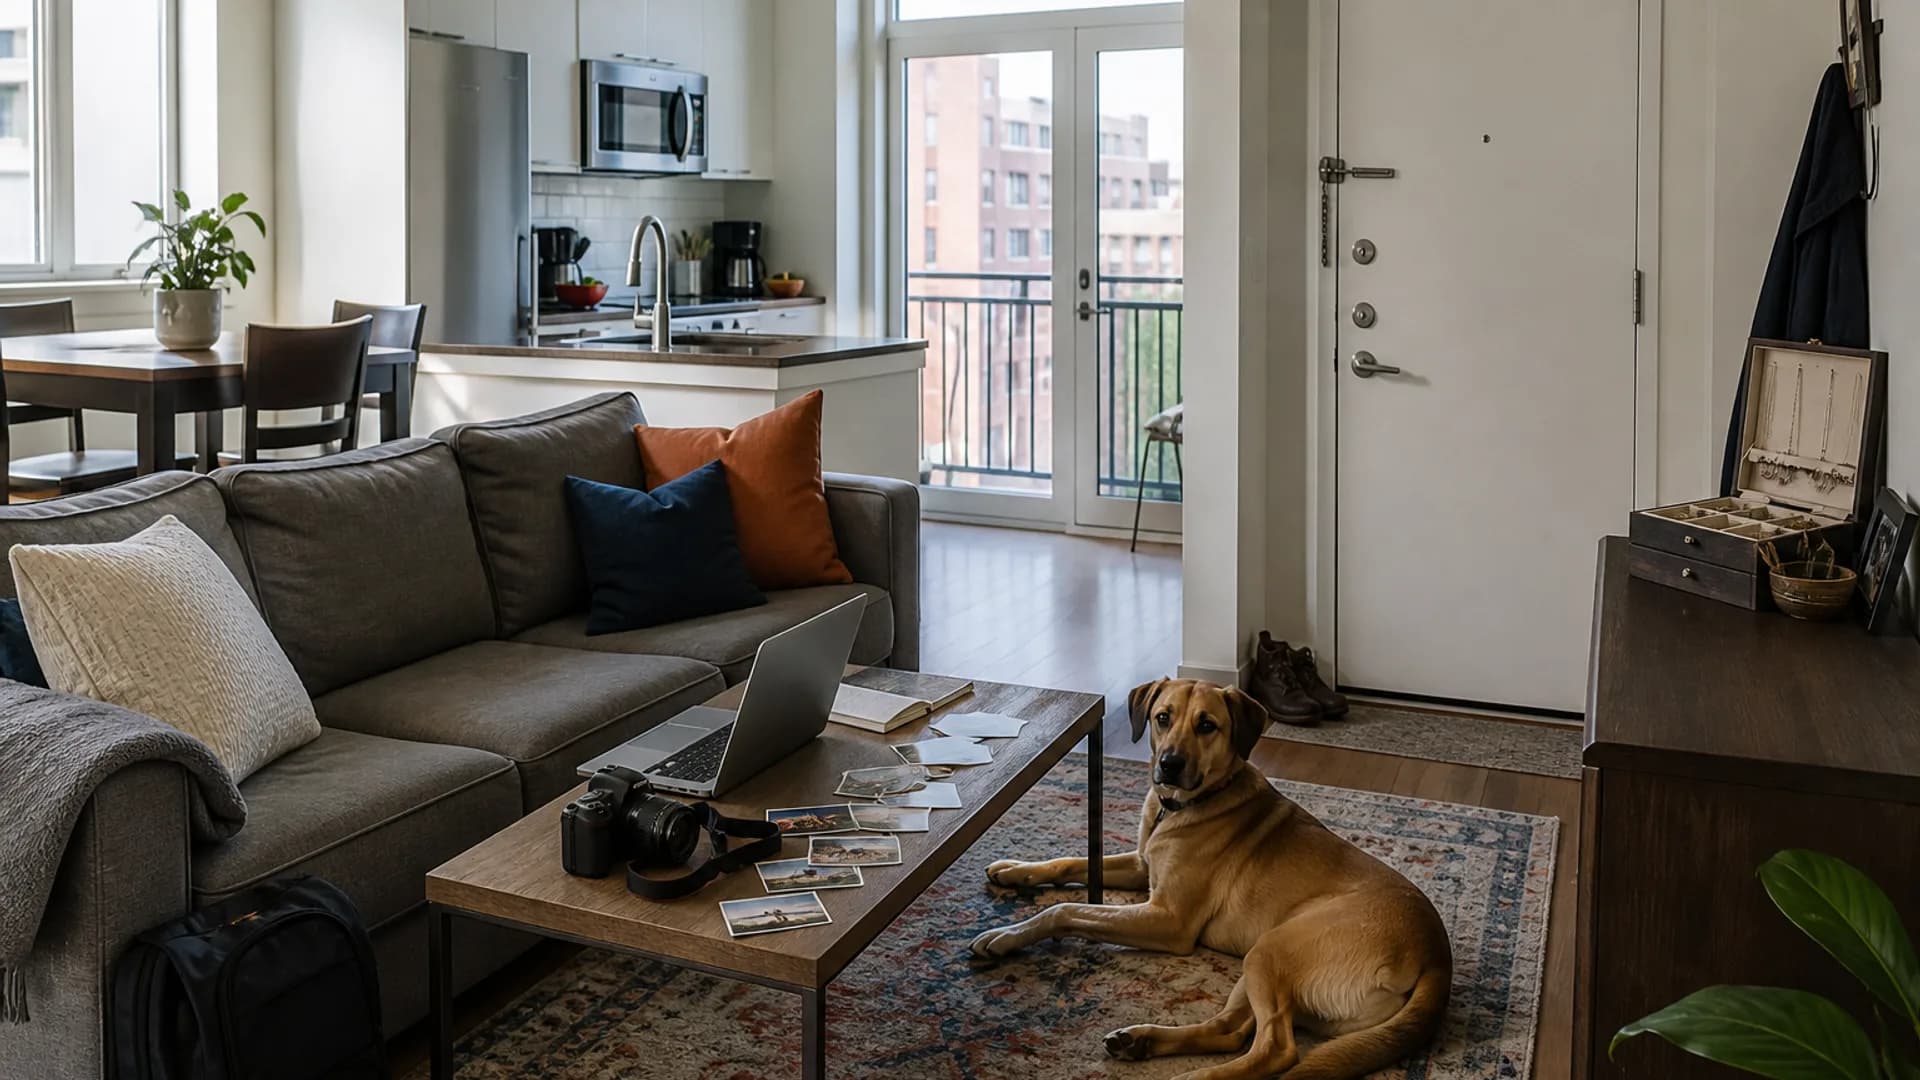
Furnished Chicagoland apartment living room with belongings, a pet, and a deadbolted entry door

Renters Insurance

Get the protection you need for your rental property

Personal property / contents

Your stuff — the landlord’s policy covers the building.

Renters insurance is built around personal property: furniture, electronics, clothing, and kitchenware. The building itself is the landlord’s or association’s problem. Limits should reflect what it would cost to replace what is in the unit, not what you paid years ago.

Learn more →

Tap a point on the apartment to learn more

Pin the add-ons that match how you use this coverage

The base renters policy is the printed form. An endorsement is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Renters policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

What is an endorsement?

A change taped onto the form

An (sometimes called a rider) amends the base policy. , , , and named-driver are all endorsements. If a certificate or a conversation promised something, it needs to appear as an endorsement — not just in an email.

Hover or tap an add-on to see when it comes up for Illinois families and businesses — then pin a short list to send to an advisor.

When you rent or lease, your landlord's insurance usually only protects the building itself—not your personal belongings. A renters policy is built around personal property, , and (loss of use) if a covered makes the apartment unlivable.

Are your personal belongings protected?

You might think that your landlord's insurance covers your personal possessions. However, that only covers the building itself. Renters insurance is the only way to protect your valuables, and it is much more cost-effective than you'd think.

What your renters policy can do

There are two parts to renters insurance. The first is property coverage for damage or loss from certain unexpected events. Be sure to check your renters insurance coverage details–there will usually be both an overall limit on the payout and a maximum amount for any one renters insurance claim. Here are a few examples of what can be covered in a renters policy:

Fire

Theft

Lightning

Wind/Hail

Liability coverage options

Another way some renters policies protect you is through liability coverage. For instance, if you accidentally damage the rental property itself or if somebody is injured while visiting you at your apartment, your insurance would cover it.

Loss of use coverage

You may also get a payment for living expenses if the rental property is uninhabitable after one of the events the renters insurance policy covers. This safety net can help you recover from such a loss that you would otherwise have to pay for out-of-pocket.

Exceptions of renters insurance

There are a few things that are not included. For example, if you park a vehicle on the rental property itself, your car usually will not be covered by renters insurance.

Whether you rent a home or a studio apartment, you cannot afford to not have renters insurance. In fact, it is extremely cost-effective. We'd be happy to walk you through the options to ensure you have the insurance coverage and protection you need.

Request a renters quote to get started.

Frequently Asked Questions

What does Renters Insurance typically cover in Illinois?
Renters insurance typically covers your personal belongings, if someone is injured in your unit or you accidentally damage others' property, and after a covered loss. The landlord's policy usually insures the building, not your furniture, electronics, or clothes. We help Illinois renters match limits and to how they actually live.
Does renters insurance cover sewer backup in Illinois?
Standard renters policies often exclude sewer and drain backup, the same way many homeowners forms do. Older Chicagoland buildings and garden-level apartments can still face backup into a unit. A is often worth reviewing when you quote or renew.
How should I choose contents limits for a Chicagoland rental?
Contents limits should reflect what it would cost to replace your belongings, not a round guess or your security deposit. Walk through rooms, include electronics and clothing, and tell us about jewelry, bikes, or work equipment that may need scheduled coverage. We help western-suburbs renters set realistic limits as they add roommates or upgrade furnishings.
When should a renter review personal umbrella limits?
Review coverage if you have substantial savings, a growing income, a teen driver on your auto policy, or a dog and frequent guests. Renters limits are often $100,000 to $300,000, which may be light if someone is seriously injured. Illinois jury awards make an umbrella a practical extra layer for many Chicagoland tenants.
Does my landlord's insurance cover my belongings?
No. A landlord's policy typically covers the building and the owner's , not your furniture, clothing, or electronics. If a fire, theft, or covered water loss destroys your things, you generally need your own renters policy. That is why many Chicagoland leases require tenants to carry renters insurance and name the landlord as additional interest.
Is renters insurance required in Illinois?
Illinois law does not require every tenant to buy renters insurance, but many leases do. Landlords in Cook, DuPage, and surrounding counties often require proof of and contents coverage before you move in. Even without a lease mandate, renters insurance is usually inexpensive compared with replacing belongings after a fire or theft.
Does renters insurance cover theft?
Yes, theft of covered personal property is typically included, subject to your and special limits on items such as jewelry or cash. Coverage often follows your belongings off premises as well, which can help if a laptop is stolen from a car or while you travel. Motorcycles, cars, and most boats still need their own policies.
Does renters insurance cover additional living expenses if I cannot stay in the apartment?
, sometimes called loss of use, typically help pay for a hotel, extra meals, and related costs if a covered loss makes your rental uninhabitable. It does not usually apply if you are displaced for an excluded cause such as flood. We review ALE limits so they match Chicagoland hotel and short-term rental costs.
Does renters insurance cover my roommate's stuff?
Usually not. A renters policy generally covers the and household members listed on the policy, not a roommate who is on a separate lease or simply sharing rent. Each roommate often needs their own policy, or you need to be added as named insureds where the carrier allows it. We help households in Roselle and nearby suburbs sort that out before a claim.
How does an independent agency help me compare Renters options?
As an in Roselle, we compare Renters Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.

Endorsements and add-ons

The same renters policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Additional interest / landlord listing

Endorsement

Shows the landlord on evidence of insurance when the lease asks.

Leases often require proof of renters insurance and that the landlord be listed. Listing them as additional interest is not the same as adding them as an on . We match the certificate to the clause instead of guessing.

Earthquake

Endorsement

A buyback Illinois renters sometimes add, with a separate deductible.

Earthquake is typically excluded and added by or a companion form, with a percentage . The New Madrid conversation is more relevant downstate, but some Chicagoland renters still ask. It is not a substitute for or flood.

Flood insurance (contents)

Separate policy

Contents flood is not on a standard renters form.

If you keep belongings in a basement apartment near a creek or in a mapped zone, flood contents coverage is a separate policy. The landlord’s building flood policy, if any, does not replace your sofa. is still a different .

Learn more →

Identity theft

Endorsement

Limited restoration expenses after a documented identity event.

Apartment living does not reduce mail theft or device theft. An identity theft on a renters policy is a small expense cover, not a credit-monitoring subscription. Worth a look if you already itemize bikes and electronics.

Incidental business

Endorsement

Limited coverage when you work from the rental.

Clients in the unit, product inventory, or a photography studio can trigger a business on a renters form. An incidental business may restore a slice of property and . A separate is the next step if the activity is more than incidental.

Increased additional living expense

Endorsement

Raises the limit if a fire makes the apartment unlivable.

pays for a hotel or extra rent while the unit is repaired after a covered . The default percentage of contents may be thin in Chicago-area hotel markets. An increased ALE , or simply a higher contents limit, can keep that from running out mid-stay.

Personal umbrella

Separate policy

Extra liability if someone is hurt in the unit or you cause a serious auto claim.

Renters still have — a guest injured in the apartment, or a dog-bite claim. sits over renters and auto. It is a separate policy, useful once there are assets or a household driver with a long commute.

Learn more →

Scheduled personal property

Endorsement

Lists bikes, jewelry, cameras, or instruments by item.

Unscheduled renters contents have sublimits on jewelry, bikes, and electronics. Scheduling an item can raise the limit and, on some forms, cover more causes of loss. Bring serial numbers and appraisals. This is the same idea as a homeowners jewelry schedule, just on an HO-4.

Sewer backup

Endorsement

Drain backup into a garden apartment or unit.

Garden-level and first-floor rentals in older Chicagoland buildings take on water from drains, not just from the sky. A is often available on renters forms, with a modest limit. Flood and sewer backup are still different .

Learn more →

Waterbed / water-related furnishings

Endorsement

Liability and property for water-filled furniture where required.

Some leases still ask about waterbeds. Carriers that write the exposure usually do it by . It is a narrow form. If the lease forbids it, the endorsement does not rewrite the lease.

Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us