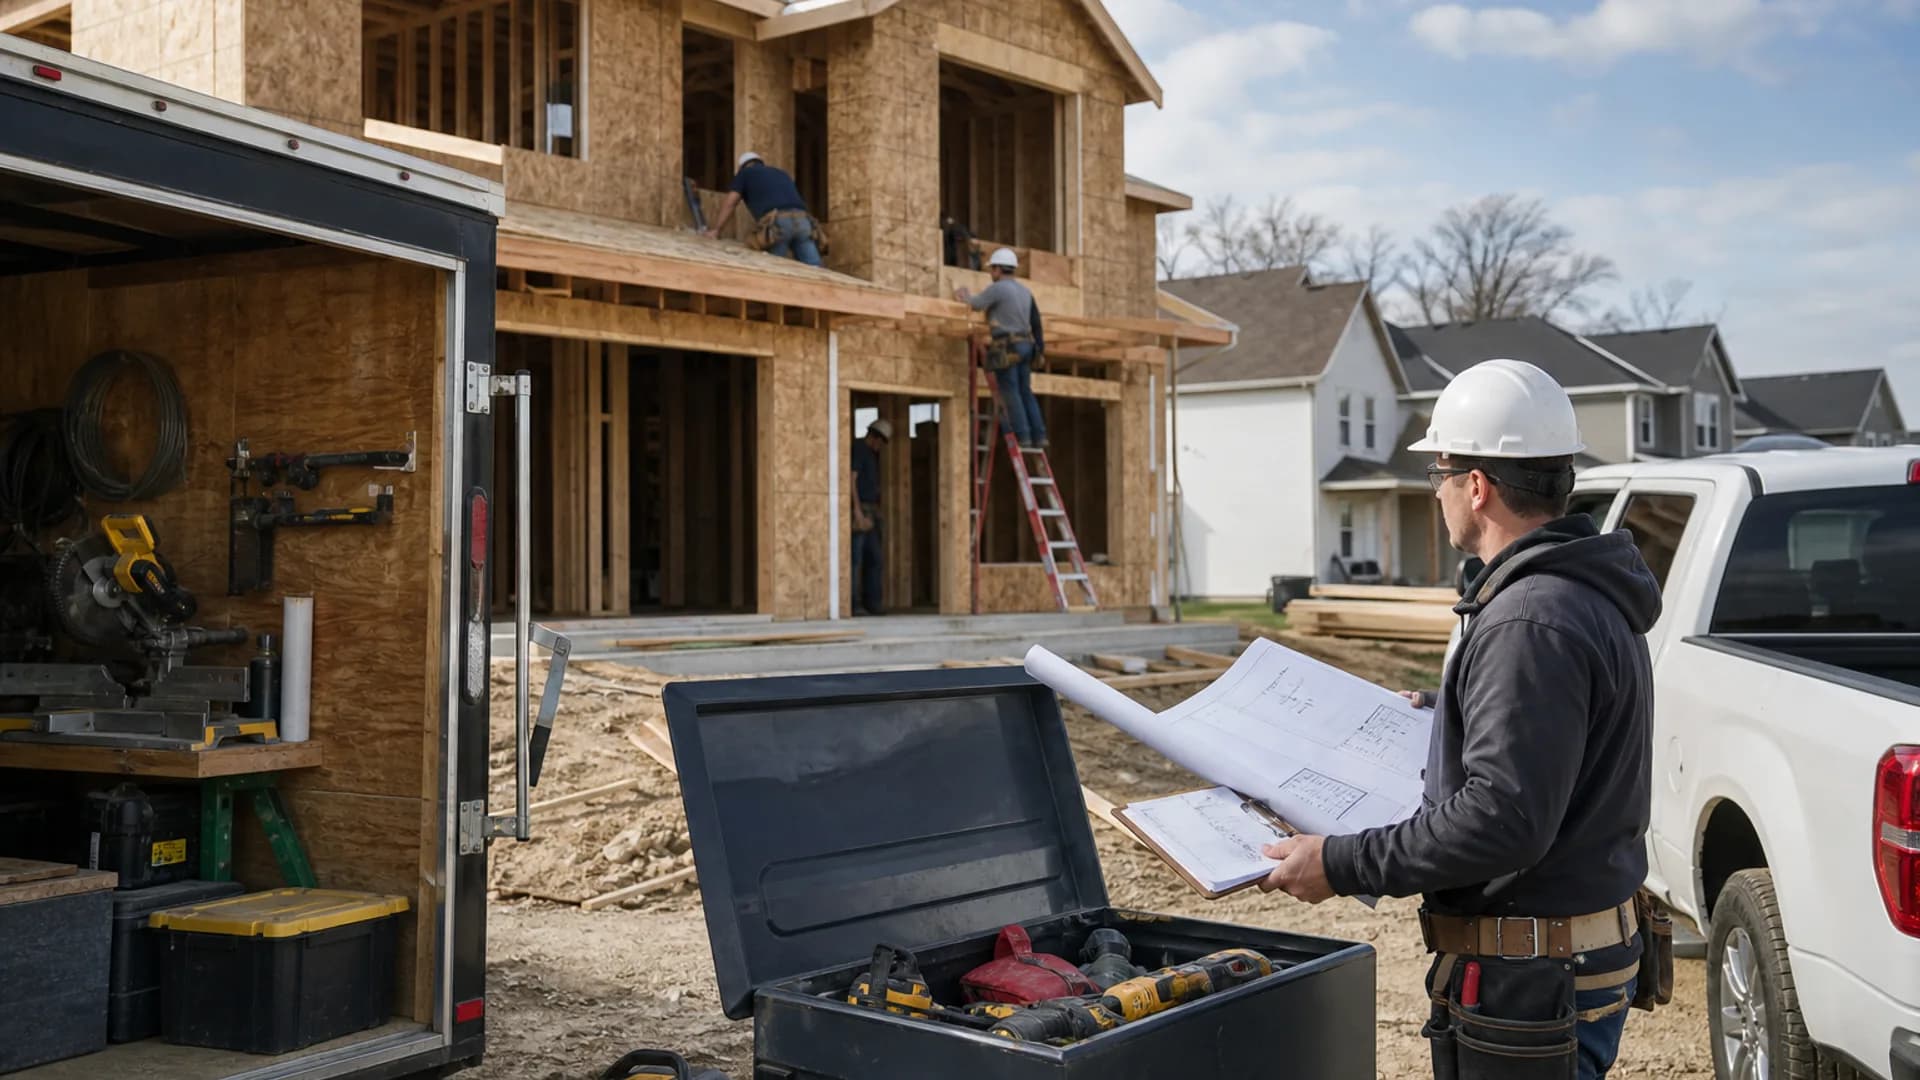
Chicagoland job site with a framed house, crew, tool trailer, work truck, and certificate paperwork

Contractor Insurance

Constructing the ideal insurance coverage

Injury or damage on the job site — or at your shop.

Contractor general liability covers claims of or caused on site or to visitors on your premises. It is often mandatory to bid public work, and project owners in the western suburbs will ask for it on the certificate.

Learn more →

Tap a point on the scene to learn more

Pin the add-ons that match how you use this coverage

The base contractor policy is the printed form. An endorsement is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Contractor policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

What is an endorsement?

A change taped onto the form

An (sometimes called a rider) amends the base policy. , , , and named-driver are all endorsements. If a certificate or a conversation promised something, it needs to appear as an endorsement — not just in an email.

Hover or tap an add-on to see when it comes up for Illinois families and businesses — then pin a short list to send to an advisor.

Contractor insurance is not one-size-fits-all. A specialized policy allows you to easily customize and simplify your insurance coverage to ensure that your business' unique needs are protected.

Most contractor contracts ask for , , a , and often or wording.

Coverage for every type of contractor

A specialty contractor insurance policy is an easy way to cover multiple risks without having to settle for a one-size-fits-all policy that wastes money on coverage you do not need. There are a variety of options available depending on what type of contracting work your business does. From general contractors to HVAC technicians, plumbers, carpenters, electricians, painters, and the like, specialized contractor insurance can ensure your business has the right level of coverage.

The benefits of general liability for contractors

A good policy includes general liability that covers you against claims of damage or injury caused on site or to visitors on your own premises. Such costs can be immense and general liability insurance is often mandatory if you want to bid for government contracts.

Protection for the equipment you use

You should also make sure that you protect your stock, machinery, and equipment against damage or loss from fire, theft, flooding, and other risks, both on-site and off-site. Just as importantly, you need to have insurance coverage against loss of income if you are unable to carry out work because your equipment is damaged.

Coverage for your employees

Remember also to get workers' compensation insurance, which is usually mandatory and protects employees against lost income and medical bills resulting from workplace injuries. You might be worried that the costs of a workers' compensation policy will be high given the inherent risks of construction work, but many insurers will offer discounts if you follow safety programs.

If you need any help choosing the right contractor insurance policy, Reach out to our team when you are ready to review options.

Request a contractor quote to get started.

Frequently Asked Questions

What insurance do Chicagoland contractor contractors typically need?
Most contractors carry , when employees are involved, and commercial auto for work vehicles. Tools, equipment, and completed operations exposures may need additional .
Can you provide certificates for Chicagoland project owners?
Most active clients receive ACORD certificates the same business day. We align and requirements with your contracts.
How do seasonal Illinois weather risks affect contractor policies?
Freeze-thaw cycles, heavy rain, and winter job-site conditions can increase property and exposures. We review completed operations and coverage before busy seasons.
Does my personal auto policy cover work trucks?
Personal auto policies usually exclude business use and commercial hauling. Business auto or commercial policies are typically required when vehicles are used for jobs, tools, or employees.
Does general liability cover my tools and equipment?
No. pays when you injure someone or damage others' property; it does not replace your own tools stolen from a truck or jobsite. That exposure belongs on or contractors equipment coverage. A Chicagoland remodeler's saws, ladders, and compressors are often the largest uninsured asset until we schedule or blanket them.
Do Illinois contractors need workers compensation?
If you have employees, Illinois generally requires . Solo owner-operators may have more flexibility, but many general contractors, municipalities, and project owners still require a workers comp certificate, including waivers when you use subs. We check payroll class codes and 1099 versus W-2 relationships before you bid.
What is completed operations coverage?
Completed operations is the part of that applies after you leave the job—for example, a water leak from work you finished last year. Ongoing operations covers the job while you are still on site. Project owners in the western suburbs routinely require completed operations to stay in force after substantial completion. We confirm the term and any residential project limitations.
What does additional insured mean on a certificate?
status extends certain protection to the project owner, general contractor, or landlord named on your certificate. The wording matters as much as the checkbox. Ongoing operations versus completed operations, primary and noncontributory language, and are common Chicagoland contract asks. We match the form to the contract instead of issuing a blank ACORD.
Does general liability cover defective work or callbacks?
Typically not for the cost to redo your own faulty workmanship. GL is meant for resulting or , not the cost of repairing your defective installation. Callbacks, rework, and "your work" surprise contractors at claim time. We talk through what GL will and will not do before you rely on it as a warranty.
Why use an independent agency for Contractor Insurance?
As an in Roselle, we compare Contractor Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.

Endorsements and add-ons

The same contractor policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Additional insured — ongoing operations

Endorsement

Covers the GC or owner while you are still on the job.

CG 20 10-style ongoing operations is what most bid packets mean by “AI.” The certificate is not the . Blanket additional insured helps when every GC uses a different legal name. Wording still has to match the contract.

Contractors equipment / inland marine

Endorsement

Tools, trailers, and gear that move from job to job.

A or GL form is not a tool policy. (contractors equipment) covers scheduled or blanket tools, including theft from a truck — with warranties about locking and overnight storage. Jobsite theft in Cook County is why we write it.

Learn more →

Employee tools

Endorsement

Employees’ own tools stolen or damaged on the job.

Crews bring their own saws and meters. Employee-tools coverage is a small inland-marine style limit. It is goodwill and retention as much as risk transfer. It does not replace the employee’s homeowners policy for tools at home.

Hired and non-owned auto

Endorsement

Rented vans and employees in personal trucks on company time.

Sending a carpenter to Menards in a personal pickup is . Renting a cube van for a weekend is . Neither is on the GL form. A real work fleet belongs on commercial auto.

Installation floater

Endorsement

Materials and fixtures you are installing until the job is accepted.

Cabinets, windows, or HVAC units sitting in a house you do not own yet are not “your building.” An installation covers that property during transit and installation. is a different form when you are the project’s property coverage.

Leased / rented equipment

Endorsement

The machine you rented that the rental house requires you to insure.

Rental contracts shift damage to you. A rented-equipment (or an schedule) is how you avoid buying the rental house’s expensive waiver blindly. Check the daily rental value against the limit.

Per-project aggregate

Endorsement

A fresh general aggregate for each job instead of one shared pot.

A busy remodeler can burn a single across jobs. Per-project (or per-location) aggregate gives each job its own cap. GCs like seeing it on the certificate. It is an , not a higher occurrence limit.

Primary and noncontributory

Endorsement

Your policy pays first; the GC’s policy does not share.

Primary and noncontributory wording is a contract staple in Chicagoland construction. Without the , “” may still contribute beside the GC’s policy. Bid documents usually require both AI and P&NC.

Residential vs new-construction limitation

Endorsement

Some contractor forms restrict tract homes or condos — or can buy them back.

Carriers love to limit new residential, condo, or apartment work. If that is your book, we either endorse the limitation off or move the account. A surprise residential after you bid a townhome job is an expensive way to learn the form.

Unmanned aircraft (drone)

Endorsement

Limited liability if you fly a drone on the job.

Roof inspections and marketing shots are drone exposures. Some packages offer a small unmanned-aircraft ; larger operations need a dedicated aviation conversation. FAA rules are not insurance.

Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us