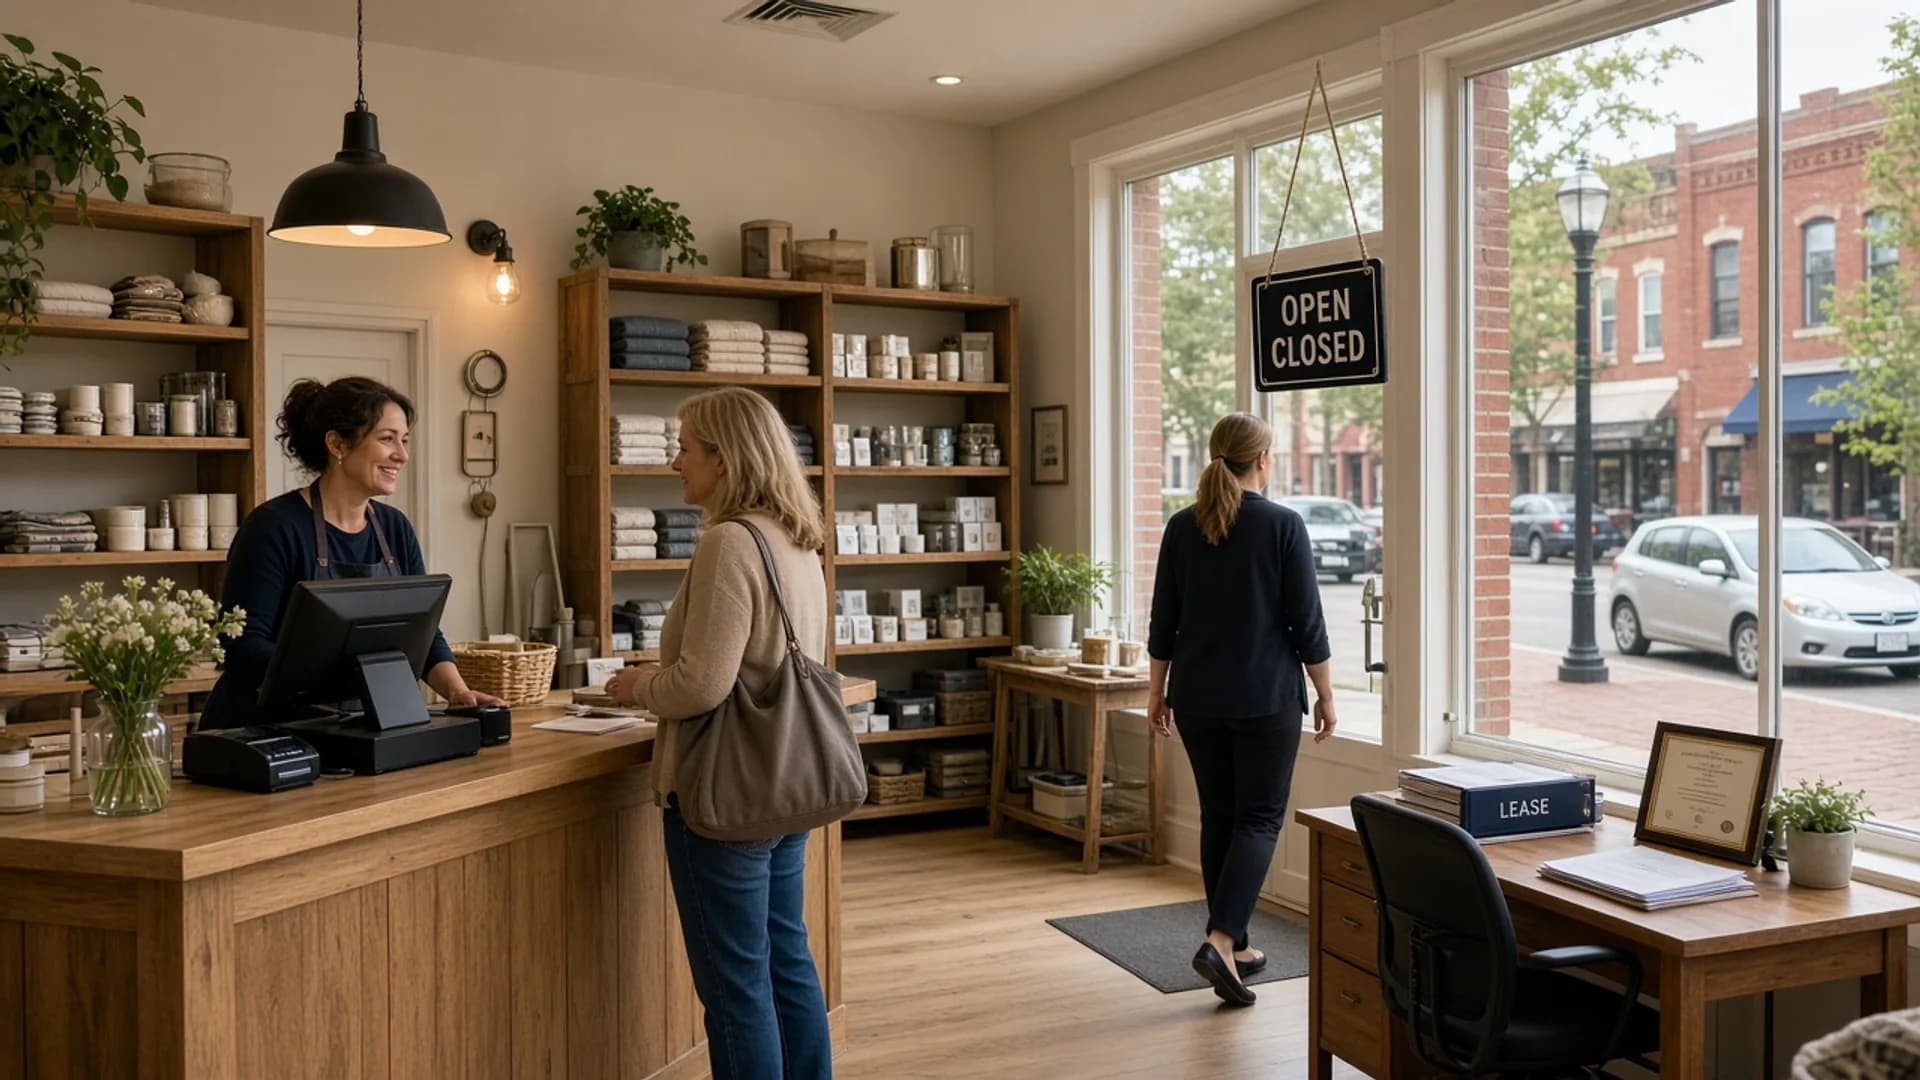
Chicagoland storefront with customers, a POS counter, inventory, staff, and a car at the curb

Business Owners Insurance

Insurance coverage for businesses of all sizes

Customer injury in the store — slips, falls, and damaged belongings.

A ’s side responds when a guest is hurt on the premises or you damage someone’s property. Illinois storefronts start here. It is not , not , and not auto.

Learn more →

Tap a point on the scene to learn more

Pin the add-ons that match how you use this coverage

The base business owners policy is the printed form. An endorsement is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Business owners policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

What is an endorsement?

A change taped onto the form

An (sometimes called a rider) amends the base policy. , , , and named-driver are all endorsements. If a certificate or a conversation promised something, it needs to appear as an endorsement — not just in an email.

Hover or tap an add-on to see when it comes up for Illinois families and businesses — then pin a short list to send to an advisor.

A (BOP) combines business property and business into one convenient policy. We will work with you to design coverage that protects your business from a variety of risks, unique to your industry.

A businessowners policy packages with property; fleet and business auto add or when employees drive their own cars on the clock.

Why does your business need business owners insurance?

Because your business faces the unexpected on a daily basis, there are always risks involved. Whether it is the risk of damage or loss to your property or customers, the only way to protect your business is with the right policy. With the convenience of a BOP, you can minimize the risks and focus on the future of your business.

Two coverages in one policy

A business owners insurance policy is known as BOP for short. This is appropriate, since it offers a one-two punch. It is a combination policy bringing together two types of coverages.

Includes property insurance

The first type is property insurance. Property insurance covers risks associated with your business' premises, equipment and vehicles. In addition, it often includes any associated loss of business. This is an essential coverage because it ensures your business, assets, and income are protected. For instance, here are a few of the coverages to consider in your business owners policy:

Fire

Flooding

Theft

Accidental Damage

Loss of Income

Loss/Damage of Property

Also includes liability insurance coverage

The second type is liability insurance. Liability insurance covers damage to people you deal with and their property. However, it is important to note that liability insurance usually does not cover risks related to professional services–meaning damages that result from you giving clients inaccurate advice, for instance. The liability coverage included in your business owners policy is a necessity, especially if:

You meet your clients at your business or theirs.

You have physical access to your clients' equipment.

There is a risk of damage to people or business.

Customized coverage for your business

Getting a business owners policy (BOP) means covering all these risks in one go, which significantly reduces stress and brings you peace of mind. Polices are typically custom made to cover your specific needs, and pricing varies depending on your business. But, it is normally cheaper than buying separate policies for each element.

Understanding your unique business needs

Designing a business owners policy that works best for you and your business is what we do best. We are focused on understanding your business so we can develop the right policy to protect your business, income, and assets. Most importantly, we want your business to be successful. Finding the right BOP coverage to meet your needs is the best place to start.

So, no matter what kind of business your run, consider the benefits of business owners insurance. From startups to established businesses, we will develop a custom plan for you. Reach out to our team when you are ready to review options. to get started!

Request a business owners quote to get started.

Frequently Asked Questions

What does Business Owners Insurance typically cover for Illinois businesses?
Coverage varies by industry and carrier, but we start with your operations in the Chicagoland area and statewide exposures. We align limits with contracts, leases, and Illinois regulatory requirements rather than selling generic templates.
What limits do Chicagoland contracts usually require?
Leases, vendor agreements, and project owners often specify minimum limits and certificate wording. We review your contracts and align policies accordingly.
How quickly can I get a certificate of insurance?
Most active clients receive ACORD certificates the same business day. We know Chicagoland vendors and landlords often need proof before you start work.
What common claims do businesses face related to Business Owners?
Claims depend on your operations, but , customer injuries, and contract disputes are frequent themes. Proper limits and reduce gaps when a loss occurs.
What is a BOP versus buying general liability and property separately?
A packages and commercial property — and often business income — into one form for eligible small and mid-size storefronts. Separate policies can fit larger or more complex risks. Eligibility depends on occupancy, size, and class. We compare a BOP against a package for Illinois operators instead of forcing a one-size form.
Does a BOP cover employees driving personal cars on company time?
Not on the unendorsed form. does not follow a bank run or a supply trip in a personal car. Hired and is the usual on a . A true work fleet belongs on commercial auto. Personal auto policies often exclude business use.
Does a BOP include workers compensation?
No. A packages property and . Illinois employers with employees generally need a separate policy. Landlords and vendor contracts still ask for both on the certificate. We place them as a pair so a claim against an employee is not a coverage argument.
Does a BOP cover professional liability or errors and omissions?
Typically not. The on a is premises and operations — a customer slip, not bad advice. Accountants, consultants, and similar professions need a separate professional-liability or policy. Mixing those facts into a BOP claim is a common surprise. We split them when the work is advice, not a storefront.
Does a BOP cover flood?
Usually not. Flood from a rising body of water is typically excluded and may need a separate flood policy. is a different . Chicagoland storefronts still take water from drains after a storm. We do not treat flood and sewer as one coverage.
Why use an independent agency for Business Owners Insurance?
As an in Roselle, we compare Business Owners Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.

Endorsements and add-ons

The same business owners policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Cyber liability

Separate policy

POS, customer lists, and payment cards.

A ransomware event on the register is not a burglary claim. Cyber is almost always a separate policy or a dedicated with its own application. The covers fire and slips; it does not automatically cover stolen card data.

Employee dishonesty / crime

Endorsement

Theft of money or inventory by an employee.

Cash drawers and stock walk out with employees more often than with burglars. Employee dishonesty is a crime , not . Limits should reflect how much cash and merchandise sit on site.

Equipment breakdown

Endorsement

Sudden mechanical or electrical failure of HVAC and equipment.

Property insurance treats mechanical breakdown as wear and tear. Equipment breakdown (boiler and machinery) is the buyback for a compressor, a panel, or a boiler. Pair it with business income if the storefront cannot open without that system.

Ordinance or law

Endorsement

Code upgrades after a partial loss to an older storefront.

Older Main Street buildings often need sprinkler, accessibility, or electrical upgrades after a fire. coverage is how you pay for that increment. The base building limit rebuilds what was there, not what the village now requires.

Sewer backup

Endorsement

Water that comes up through drains — not flood.

Sewer and drain backup is an on most forms. Flood from a rising body of water is a different and usually a different policy. Chicagoland storms make both conversations worth having, separately.

Utility services / off-premises power

Endorsement

Income and spoilage when the outage starts off your property.

A neighborhood outage can shut a storefront without damaging your building. Off-premises power and utility-services extend business income (and sometimes spoilage) to that fact pattern. The unendorsed often stops at the property line.

Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us