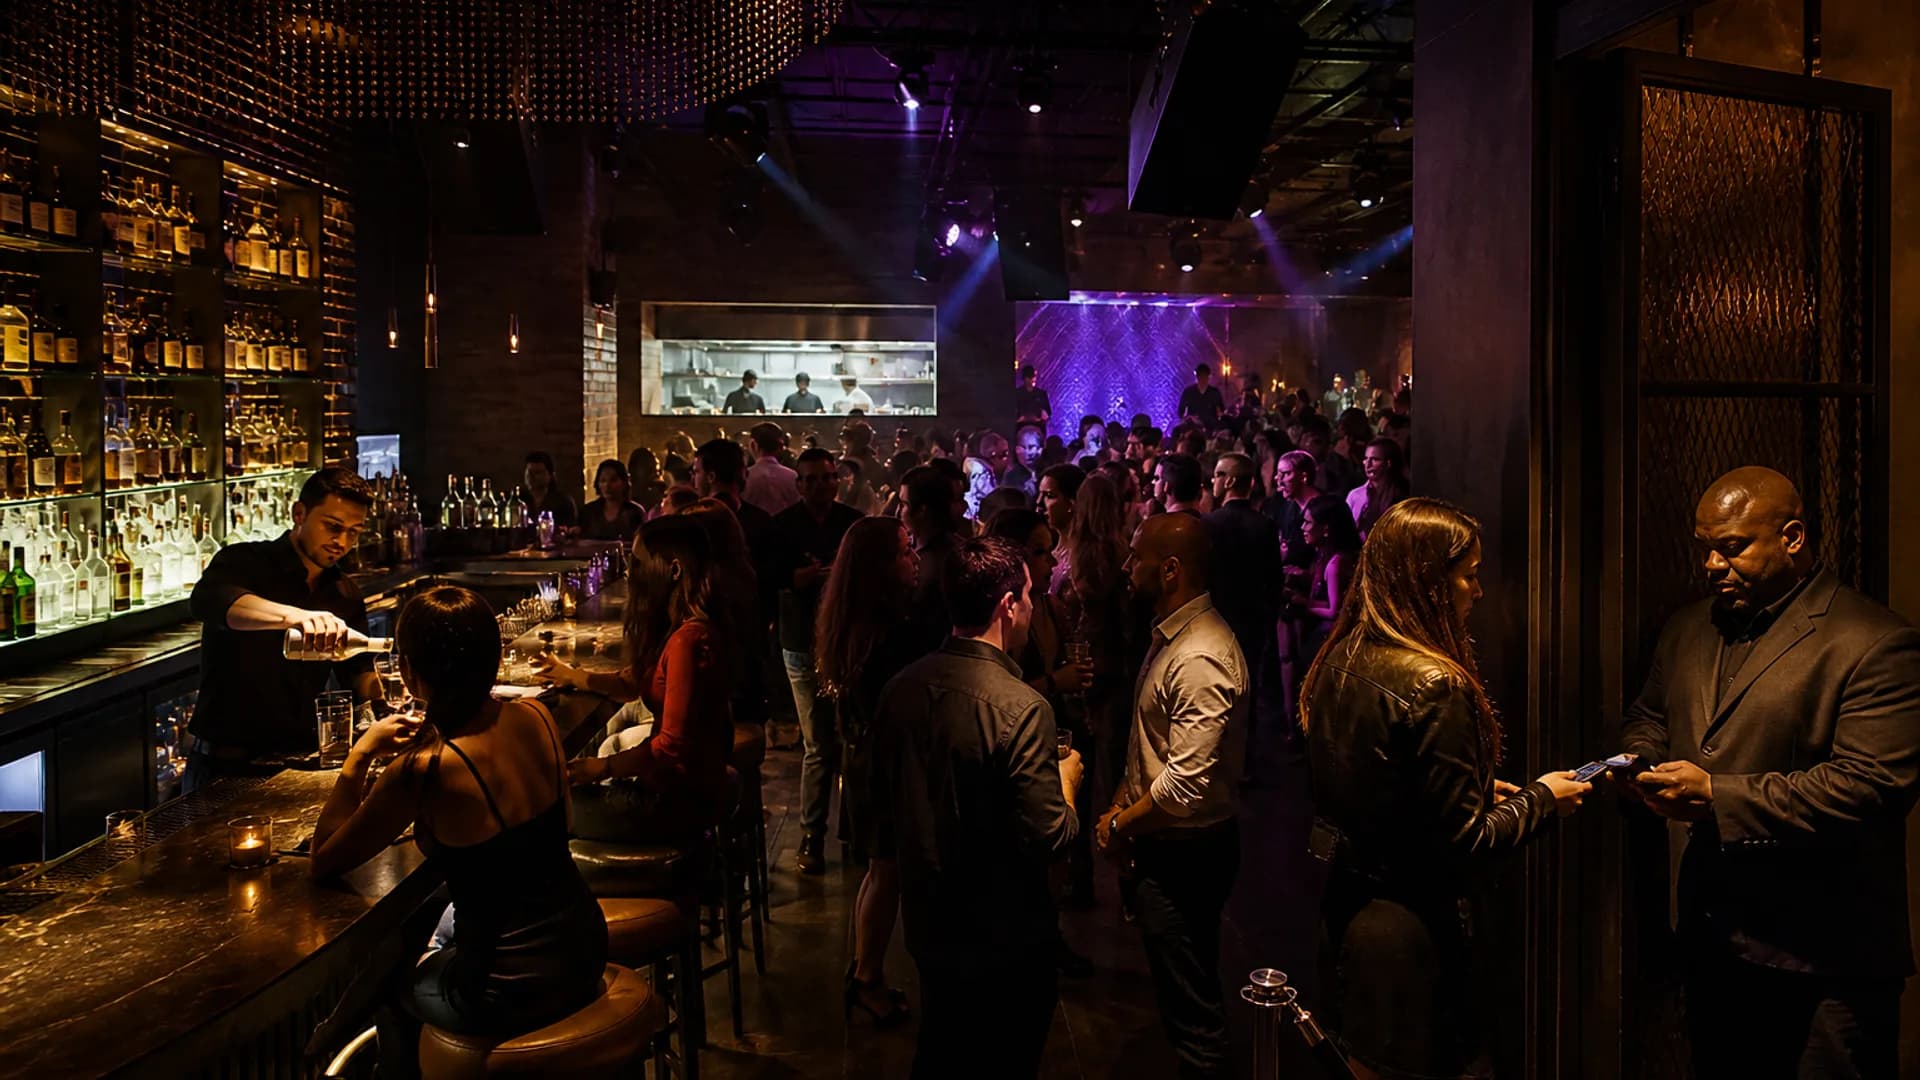
Nightclub interior with a bar, dance floor, door security, stage lighting, and a kitchen pass

Nightclub and Bar Insurance

Protecting your business so the party can rage on

Liquor

A must-have where alcohol is consumed on premises.

If someone who has been drinking in your nightclub or bar causes injury or damage, you can be held liable. Illinois dram-shop rules make liquor liability essential — and defending an unfounded claim is still expensive without it.

Learn more →

Tap a point on the scene to learn more

Pin the add-ons that match how you use this coverage

The base nightclub and bar policy is the printed form. An endorsement is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Nightclub and bar policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

What is an endorsement?

A change taped onto the form

An (sometimes called a rider) amends the base policy. , , , and named-driver are all endorsements. If a certificate or a conversation promised something, it needs to appear as an endorsement — not just in an email.

Hover or tap an add-on to see when it comes up for Illinois families and businesses — then pin a short list to send to an advisor.

Insuring a nightclub or bar is not the same as insuring any other business. These establishments require specialized coverage that takes into consideration the unique risks that nightclubs and bars face.

Coverage for the risks of owning a nightclub or bar

You know how to draw in the crowds and serve up a good time for your clientele. Your insurer needs to know what coverage is necessary to protect your business. Purchasing a customized nightclub and bar insurance package that focuses on the particular risks your business faces is essential.

The importance of liquor for your business

For example, a liquor liability policy is a must-have for any place of business where alcohol is consumed. If someone who has been drinking in your nightclub or bar causes damage or injures someone, you can be held liable. Even if unfounded, these claims can be costly to defend.

Protect your business and your property

Your property is vital to your business. If something were to happen to the building itself, you may not be able to open your business for a period of time. Consider policy options that include not only property coverage, but also your income should your business be inaccessible. And if your suppliers are unable to make deliveries that would force you to shut down temporarily, there's a policy for that, too.

The business side of nightclubs and bars

And since you are running a business, you need also need , , , as well as employment practice liability insurance.

To learn more about how specialized insurance can benefit your operation, Reach out to our team when you are ready to review options.

Request a nightclub and bar quote to get started.

Frequently Asked Questions

What does Nightclub and Bar Insurance typically cover?
Policies often combine property, , liquor where applicable, and business interruption. Kitchen equipment, food spoilage, and customer injury exposures should be reviewed together.
Do Illinois restaurants need liquor liability coverage?
If you serve alcohol, liquor is usually essential and may be required by landlords or liquor license rules. It addresses claims tied to alcohol service beyond standard .
How does business interruption coverage help food businesses?
A fire, equipment failure, or covered property loss can shut down service for days or weeks. Business interruption may help replace lost income and ongoing expenses while you recover.
Can you provide certificates for landlords and vendors?
Most active clients receive ACORD certificates the same business day. We align limits with lease requirements common in Chicagoland commercial spaces.
Does general liability cover alcohol-related claims at a bar?
Usually not. typically excludes claims arising from serving or selling alcoholic beverages. A nightclub or tavern needs a liquor policy for dram-shop type injuries after a patron leaves. We place GL and liquor together so a fight, slip, or over-service claim is not bounced between forms.
What is assault and battery coverage for nightclubs?
Many policies restrict or exclude assault and battery, which is a common claim when security separates patrons or a fight spills onto the sidewalk. Specialty nightclub markets often add assault and battery by with its own limit. Chicago and suburban venues with bouncing, late hours, or live music should treat this as a core term, not a footnote.
Why is nightclub and bar insurance more expensive than restaurant insurance?
Nightclubs combine alcohol sales, late hours, crowds, entertainment, and sometimes dancing or security, which produces more frequent and severe claims than a daytime restaurant. Carriers also scrutinize occupancy, door policy, and prior losses. That is why a standard restaurant is often the wrong form. We use markets that actually write Illinois bars instead of forcing a restaurant rate.
Does bar insurance cover security staff or bouncers?
Injuries involving security are insurable only if the carrier knows you use them and the form does not exclude assault, battery, or independent contractor guards. Some venues need the security firm to carry its own and name the club . We review employee versus contracted security before a weekend opening in the Chicagoland market.
What is Illinois dram shop liability?
Illinois dram shop law can hold a business that sells or gives alcohol responsible when an intoxicated person causes injury or death. That statutory exposure is why liquor exists and why over-service training matters. Limits, , and whether you cater off-premises all change how a claim would be defended. We explain the coverage in policy language, not slogans.
Why use an independent agency for Nightclub and Bar Insurance?
As an in Roselle, we compare Nightclub and Bar Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.

Endorsements and add-ons

The same nightclub and bar policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Assault and battery buyback

Endorsement

Limited liability the nightlife form otherwise excludes.

Assault and battery is the nightlife accounts live or die on. Many carriers exclude it entirely; others sell a sublimited buyback with security warranties — ID checks, cameras, licensed staff. A door incident is not a typical premises slip-and-fall.

Contractual liability / hold harmless

Endorsement

Lease and vendor hold-harmless agreements the GL may not fully assume.

Nightlife is contract-heavy: talent, security, landlords. The GL contractual- limitation can leave a hole if you assume someone else’s liability too broadly. We read the hold harmless against what the form actually picks up.

Cyber liability

Separate policy

POS, membership lists, and camera systems.

Cover charges, tabs, and ID scanners collect data. Cyber is typically a separate policy. A ransomware event on the POS is not a burglary claim. Cameras that record the door also create a data conversation.

Employee benefits liability

Endorsement

Claims that you mishandled employee benefit administration.

If you offer health or retirement benefits, EBL is a small professional- style for admin errors — not the health plan itself. It shows up on packages more often than owners expect.

Equipment breakdown

Endorsement

Draft systems, HVAC, and kitchen equipment that suddenly fail.

Nightlife buildings run hard on HVAC and refrigeration. Equipment breakdown covers sudden mechanical or electrical failure that property insurance calls wear and tear. Pair it with spoilage if the cooler is the business.

Hired and non-owned auto

Endorsement

Managers’ cars and occasional rentals — not a party bus fleet.

Running to the distributor in a personal vehicle, or renting a van for a festival weekend, is hired/ on the package. A true shuttle or limo operation needs commercial auto and different filings.

Liquor liability

Separate policy

Dram-shop — almost never sitting inside general liability.

Selling drinks in Illinois is a liquor policy, not a GL checkbox. Assault-and-battery and liquor sometimes interact in ugly ways; we keep them distinct. Host liquor for a private party is not a nightclub program.

Learn more →

Special event / promoter

Endorsement

One-off shows that fall outside the usual operations.

A ticketed concert, festival pop-up, or outside promoter can sit outside the regular nightlife policy. Sometimes the answer is an ; sometimes it is a separate event policy. Tell us before the date is on Instagram.

Spoilage

Endorsement

Beer, wine, and food after a cooler or power failure.

A dead walk-in on a Saturday is inventory, not building damage. Spoilage set a refrigeration-failure limit. Maintenance records matter. This is a kitchen and bar-back issue as much as a chef issue.

Waiver of subrogation

Endorsement

Your insurer will not chase the landlord after a claim.

Lease insurance exhibits routinely require a on GL. Without the , a property or payment can still lead to a recovery action against the landlord. We match the lease exhibit line by line.

Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us