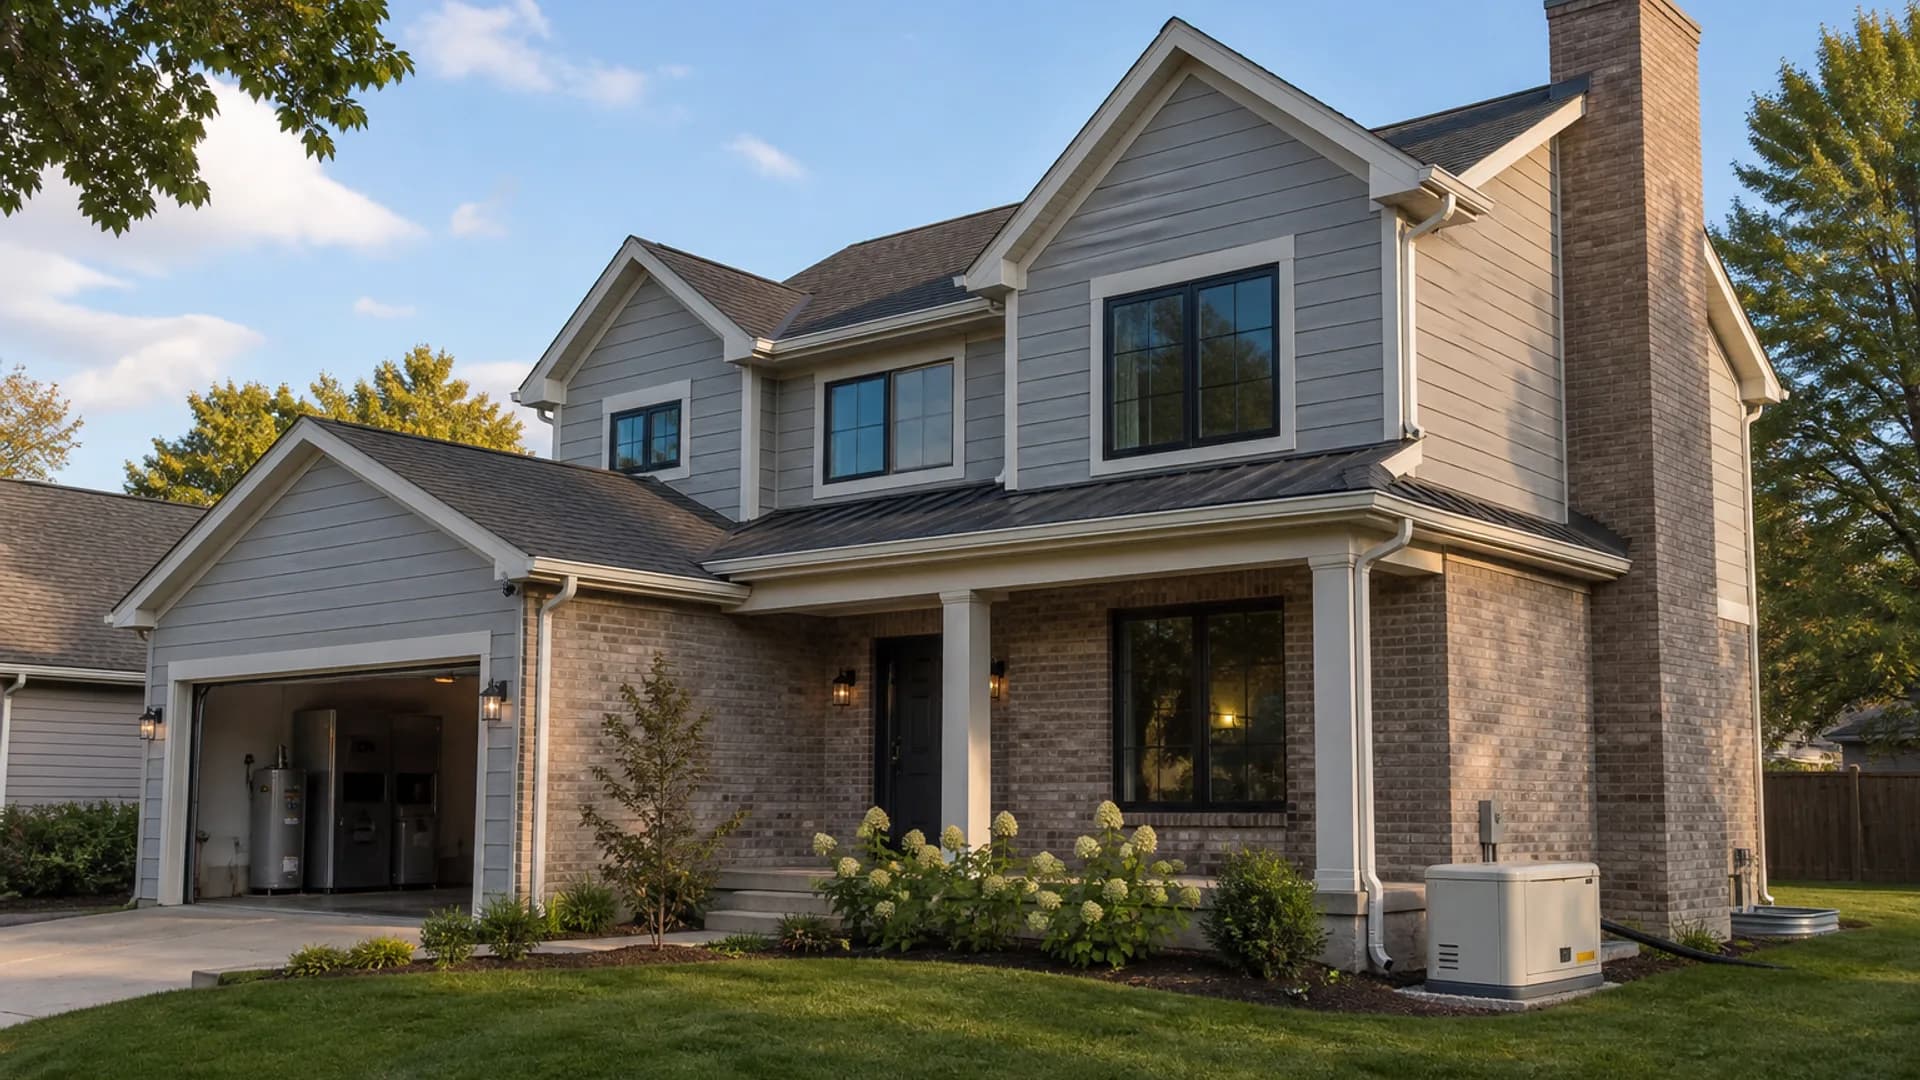
Suburban Illinois home with roof, siding, windows, chimney, trees, gutters, generator, and an open garage

Home Insurance

Coverage that protects your biggest asset

Metal or impact-rated roof

Hail and wind resistance carriers notice first.

Class 4 impact-rated or metal roofing can reduce hail claim severity and may qualify for credits with some carriers. In the Midwest, roof age and material are among the first things underwriters review after storm season.

Tap a point on the home to learn more

Pin the add-ons that match how you use this coverage

The base homeowners policy is the printed form. An endorsement is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Homeowners policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

What is an endorsement?

A change taped onto the form

An (sometimes called a rider) amends the base policy. , , , and named-driver are all endorsements. If a certificate or a conversation promised something, it needs to appear as an endorsement — not just in an email.

Hover or tap an add-on to see when it comes up for Illinois families and businesses — then pin a short list to send to an advisor.

Your home is likely your largest investment and the center of daily life. Home insurance helps you recover when fire, storm damage, theft, or claims threaten that investment.

Why home insurance matters

A serious loss—like a fire—can leave you rebuilding physically and financially. Even smaller problems, such as a burst pipe or stolen belongings, add up quickly. The right policy addresses both catastrophic events and everyday risks.

What a homeowners policy can include

Policies can be tailored with coverages such as:

We help you match limits to rebuild costs—not just your mortgage balance—and review endorsements that close common gaps.

Coverage that fits your home

No two homes are alike, and your policy should reflect how you live. As your insurance advisor, we look at the risks your property faces and build coverage that goes beyond bare-minimum protection.

Request a home insurance quote and we will review options with you.

Frequently Asked Questions

What does Home Insurance typically cover in Illinois?
Policies usually address or contents, , and after a covered loss. Condo and renters plans differ in what the association or landlord covers versus what you must insure yourself.
Does Illinois home insurance cover sewer backup?
Standard HO policies may exclude sewer and drain backup. Chicagoland homes—especially older neighborhoods—often benefit from a .
How should I choose dwelling limits in the western suburbs?
Limits should reflect rebuild cost, not just market value or your mortgage balance. We help western suburbs homeowners review , , and as property values and construction costs change.
When should I review personal umbrella limits?
After buying a home, adding a teen driver, or increasing net worth. Illinois jury awards and medical costs make practical layer for many Chicagoland families.
Does homeowners insurance cover flood damage in Illinois?
No. A standard homeowners policy excludes flood from rising surface water, overflowing rivers, or storm runoff that enters the home. You need a separate flood policy through the National Program or a private flood market. is a different gap and is often added by ; we help Chicagoland homeowners sort flood versus backup before a storm.
What is the difference between replacement cost and actual cash value?
pays to rebuild or replace with similar kind and quality, without deducting . subtracts depreciation, so an older roof or aging contents may settle for less than what it costs to replace them. limits should track rebuild cost in the western suburbs, not purchase price or the mortgage balance.
Does homeowners insurance cover a home-based business?
Typically only in a very limited way, if at all. Standard homeowners forms often cap or exclude business property and for clients who visit the home. A home-based consultant, daycare, or online seller in Illinois may need a or instead of relying on the HO-3. We review how you actually use the house.
Why did my homeowners insurance go up?
often rise because rebuild costs, severe-weather losses, and reinsurance prices have increased, not only because of your own claims. Roof age, updates to the home, credit-based insurance scores where permitted, and neighborhood loss history also matter. We shop multiple carriers at renewal so a single company's increase is not the only option.
Does homeowners insurance cover building-code upgrades after a loss?
Not automatically. If a fire or other covered loss requires you to rebuild to newer Illinois or municipal codes, coverage is what typically pays the extra cost. Older homes in Roselle, Elgin, and nearby towns often need this because rebuilding "as it was" may no longer be legal. We review it whenever limits are set.
How does an independent agency help me compare Home options?
As an in Roselle, we compare Home Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.

Endorsements and add-ons

The same homeowners policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Animal liability

Endorsement

Raises or restores liability for dog-bite and similar claims.

Many forms restrict or exclude certain breeds, or cap animal far below the rest of the policy. Illinois dog-bite claims are expensive. If you have a dog — or host a lot of neighborhood kids — we review whether the liability section still responds.

Equipment breakdown

Endorsement

Sudden mechanical or electrical failure of home systems.

Home systems — furnaces, well pumps, HVAC boards — can fail in ways a typical named- or even form treats as wear and tear. An equipment breakdown is closer to a mechanical-breakdown add-on than to a storm claim. Useful on houses with newer mechanicals you would rather not replace out of pocket.

Extended replacement cost

Endorsement

A cushion above the dwelling limit if rebuild prices spike.

adds a percentage — often 20% to 50% — above when labor and materials jump after a widespread storm. It is not a blank check. The home still needs to be insured close to rebuild value, not just the mortgage balance.

Flood insurance

Separate policy

A separate policy. Standard home forms exclude flood.

Overflow of a creek, storm surge, and surface water are flood — not . or private flood sits beside the homeowners policy, not on it. Even outside a mapped FEMA zone, we still talk through overland water after Illinois downpours.

Learn more →

Identity theft

Endorsement

Limited expense coverage after a documented identity event.

Some homeowners forms offer an identity theft for restoration expenses, not a full monitoring product. It is inexpensive relative to a standalone service, and it is not a substitute for freezing credit. We still flag it because people assume the HO-3 already includes it.

Matching siding or roof

Endorsement

Helps replace undamaged material so the exterior matches.

After hail, a carrier may pay only for the damaged slopes or sides. If the shingle or siding has been discontinued, the house can look patched. Matching vary widely by company. We compare them when the roof or siding is a visible, expensive finish.

Ordinance or law

Endorsement

Pays extra when code upgrades are required after a loss.

Older western-suburbs homes often need electrical, plumbing, or setback upgrades if a serious fire or storm forces a rebuild. coverage can help with the extra cost of bringing damaged portions up to current code. The base limit alone may not.

Personal injury

Endorsement

Libel, slander, and some privacy claims — not bodily injury.

Personal injury on a homeowners form is not medical bills. It can respond to alleged defamation or wrongful eviction in limited ways. HOAs, rental activity, and online disputes are where this tends to matter. It is not a substitute for or coverage.

Personal umbrella

Separate policy

Extra liability above home and auto limits.

An is its own policy, not a homeowners . It sits over auto and home after a serious injury on the property or a crash. Illinois jury awards and medical costs make this a practical layer once there is a house, a teen driver, or meaningful savings.

Learn more →

Scheduled personal property

Endorsement

Lists jewelry, fine arts, or collections at agreed amounts.

Unscheduled contents coverage usually caps jewelry and similar items at a few thousand dollars, and theft sublimits can be even tighter. Scheduling an appraisal or invoice on an can raise those limits and, on some forms, broaden the . Bring receipts or appraisals to the review.

Service line

Endorsement

Buried water, sewer, or power lines you are responsible for.

The pipe from the street to an older Roselle or Medinah house is often the homeowner’s problem, not the utility’s. A service line can help with excavation and repair when that buried line fails. It is easy to miss until a plumber’s bill arrives.

Sewer backup

Endorsement

Water that comes up through drains — not the same as flood.

A standard homeowners policy often excludes sewer and drain backup. After a heavy rain in DuPage or Cook County, that is one of the most common basement claims we see. A can put a limit back on the policy. Flood is still a separate conversation.

Learn more →
Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us