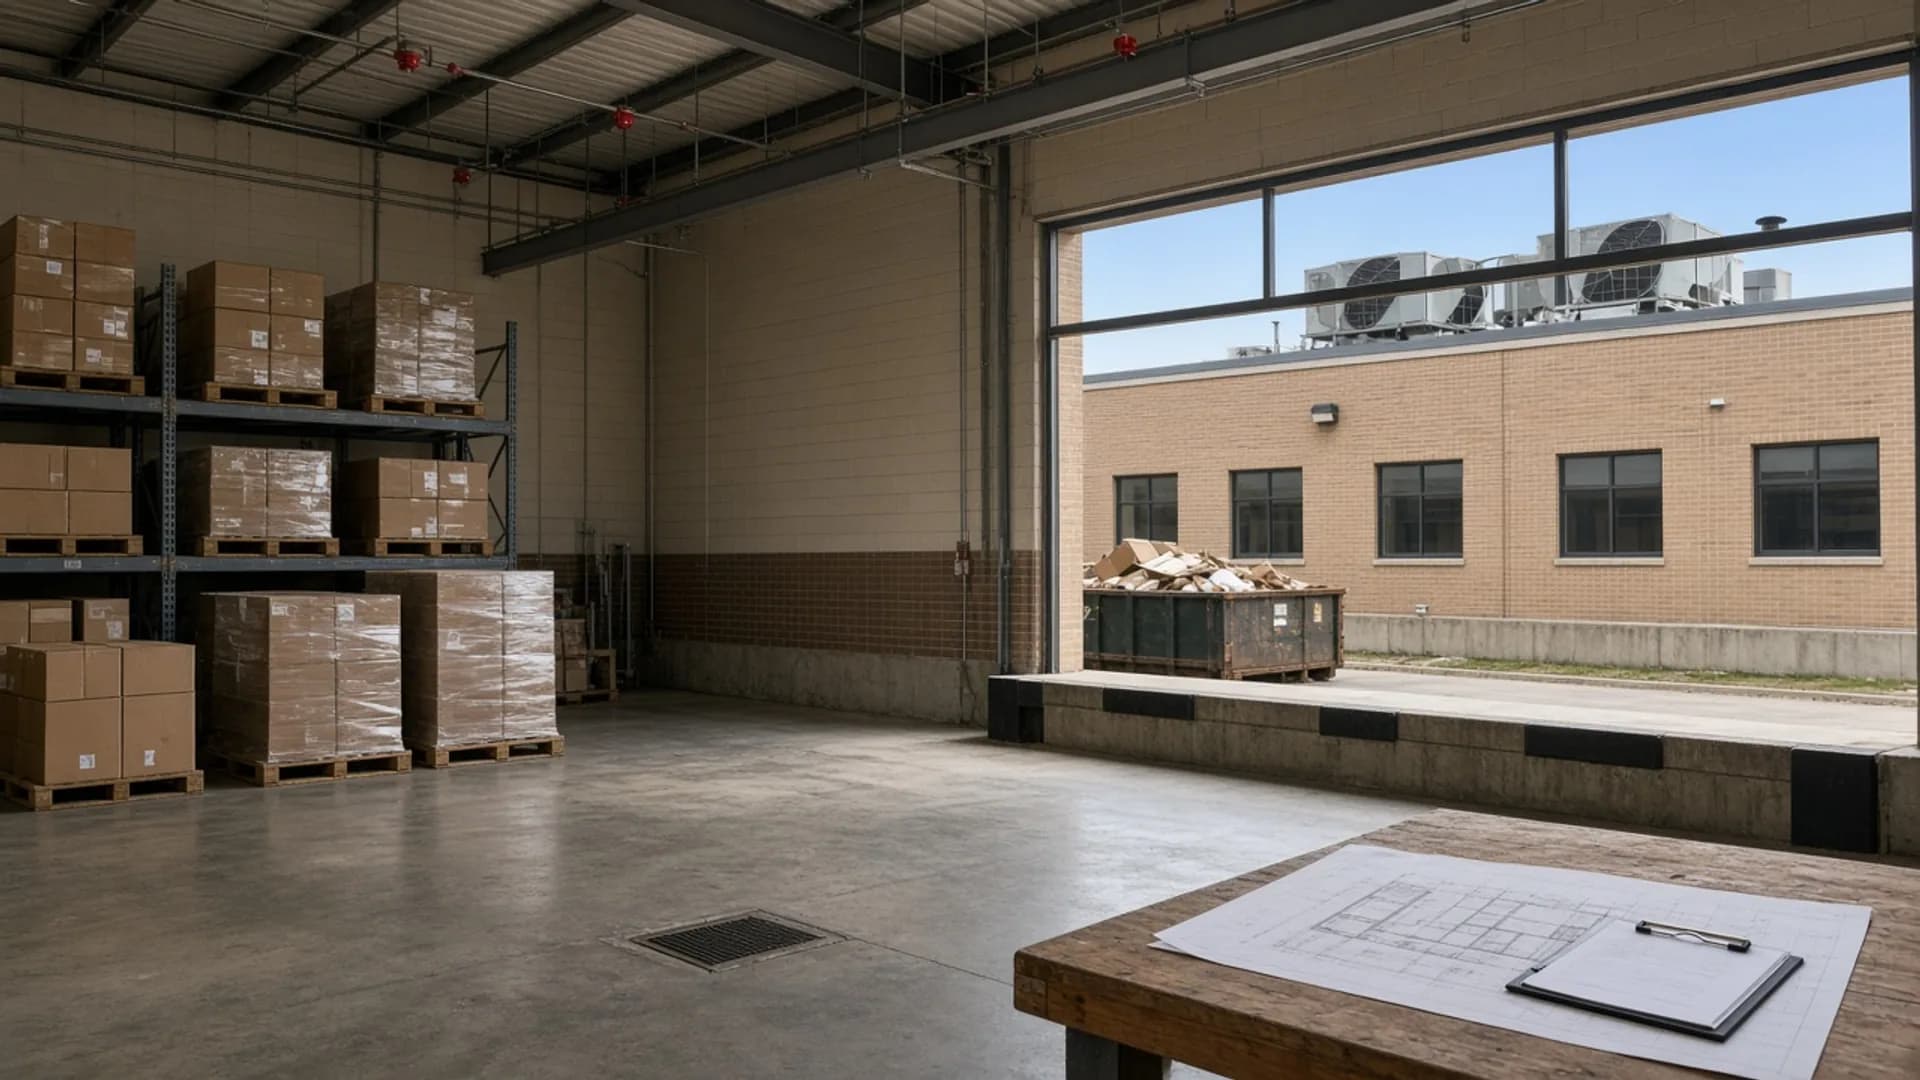
Illinois warehouse interior with masonry walls, palletized contents, sprinklers, HVAC, and a loading dock

Commercial Property Insurance

Coverage that protects your assets

Building

The structure — walls, roof, and permanently attached systems.

Commercial property starts with the building you own or are required to insure. Limits should reflect rebuild cost in Illinois, not tax-assessed value. A may be enough for a small storefront; a warehouse or older masonry building often belongs on a commercial property form.

Learn more →

Tap a point on the scene to learn more

Pin the add-ons that match how you use this coverage

The base commercial property policy is the printed form. An endorsement is a taped-on change — adding coverage, taking it away, or renaming who is insured. Optional coverages ride along with the policy. Separate policies sit beside it.

Form names and availability vary by carrier. This is a map of add-ons we commonly shop in Illinois — not a promise that every company offers every item.

Base policy

Commercial property policy

Hover an add-on to read it, then click to pin it here — a review list for your next conversation with an advisor.

Send this list to an advisor →We’ll open the contact form for this coverage so an advisor can help you decide which add-ons belong on the policy.

What is an endorsement?

A change taped onto the form

An (sometimes called a rider) amends the base policy. , , , and named-driver are all endorsements. If a certificate or a conversation promised something, it needs to appear as an endorsement — not just in an email.

Hover or tap an add-on to see when it comes up for Illinois families and businesses — then pin a short list to send to an advisor.

Commercial property insurance protects your assets in the event that they are stolen, damaged, or destroyed in a fire or natural disaster. We will partner with you to design insurance coverage that will protect your company's property.

We compare versus , the , and whether or could reduce a claim on an older building.

Is your business prepared for the worst?

Fire, flooding, theft, or accidental damage are unfortunate incidents that could not only damage or destroy your property but could also devastate your business. Whether it is buildings, commercial vehicles, or equipment, losing these assets would be a potentially critical setback for your business.

Replaces lost or damaged property

A commercial property insurance policy can protect against the cost of replacing lost or damaged property. Additionally, commercial property insurance can cover any associated losses–such as lost income–that are caused because part or all of your business is temporarily knocked out of action.

Policies can cover additional, unexpected costs

It is worth exploring the options available to you with a business property insurance policy, as they may cover risks you hadn't thought of. For example, some policies protect against the additional costs you face if rebuilding a damaged business facility means no longer being exempt from local building codes. Other points to check include whether a policy covers the cost of removing debris before reconstruction begins, as well as whether the business property is covered against weather event damage while being rebuilt.

Commercial property insurance is a great way to ensure that your business' location and assets, as well as your income, are protected. Have questions? We are happy to help!

Request a commercial property quote to get started.

Frequently Asked Questions

What does Commercial Property Insurance typically cover for Illinois businesses?
Coverage varies by industry and carrier, but we start with your operations in the Chicagoland area and statewide exposures. We align limits with contracts, leases, and Illinois regulatory requirements rather than selling generic templates.
What limits do Chicagoland contracts usually require?
Leases, vendor agreements, and project owners often specify minimum limits and certificate wording. We review your contracts and align policies accordingly.
How quickly can I get a certificate of insurance?
Most active clients receive ACORD certificates the same business day. We know Chicagoland vendors and landlords often need proof before you start work.
What common claims do businesses face related to Commercial Property?
Claims depend on your operations, but , customer injuries, and contract disputes are frequent themes. Proper limits and reduce gaps when a loss occurs.
What is coinsurance versus agreed value on commercial property?
penalizes a building insured below a stated percentage of rebuild cost, so you may share the claim. suspends that penalty when the statement of values is accepted. Illinois construction costs move; an old limit is an expensive surprise. We update values rather than hoping the coinsurance clause never applies.
What is the difference between replacement cost and actual cash value?
pays to rebuild or replace with new, similar property, subject to the limit. subtracts . After a fire in an older western-suburbs building, that gap can be large. still apply either way. We match the valuation to how you would actually rebuild.
What is ordinance or law coverage?
After a partial loss, the village may require sprinkler, electrical, or accessibility upgrades — including demolition of undamaged portions. pays that increment. The base building limit rebuilds what was there, not what the code now requires. Older Illinois masonry buildings live on this .
Does commercial property insurance cover business income?
It can, when business income and extra expense are written with the property form. Property pays to repair the building; income coverage may replace lost sales and continuing expenses while you cannot operate. Waiting periods and the period of restoration matter. We do not assume income is automatic on a building-only quote.
Does commercial property cover flood and sewer backup?
Flood from a rising body of water is typically excluded and may need a separate flood policy. Sewer and drain backup is an . Chicagoland warehouses on slabs still take water from drains after a storm. We treat flood and sewer as two conversations, not one checkbox.
Why use an independent agency for Commercial Property Insurance?
As an in Roselle, we compare Commercial Property Insurance options from multiple carriers instead of a single company menu. That helps Illinois clients find coverage that fits their risks, contracts, and budget—with local follow-up when questions or claims come up.

Endorsements and add-ons

The same commercial property policy add-ons from the explorer above, listed out. Form names and availability vary by carrier.

Agreed value

Endorsement

Suspends the coinsurance penalty when values are accepted.

penalizes a building insured below a stated percentage of rebuild cost. suspends that penalty when the statement of values is on file. We update values as Chicagoland construction costs move — an old limit is an expensive surprise.

Blanket vs scheduled limits

Endorsement

One pool of limit across locations, or a number on each building.

Scheduled limits lock each building and contents item to its own cap. Blanket can share a larger pool across locations — useful for a western-suburbs operator with more than one address. Mis-scheduling a warehouse is how people discover the difference after a fire.

Debris removal / pollutant cleanup

Endorsement

Hauling wreckage — and sometimes contaminants — after a loss.

Debris removal is often a sublimit on top of the building limit. Pollutant cleanup inside that debris can be tighter still. After a fire in an older western-suburbs building, removal can rival the repair. We do not treat it as unlimited extra.

Equipment breakdown

Endorsement

Sudden mechanical or electrical failure of building systems.

HVAC, electrical panels, and boilers fail in ways property insurance calls mechanical breakdown. Equipment breakdown is the that buys that back. A July rooftop-unit failure is not automatically a fire claim.

Ordinance or law

Endorsement

Code-driven rebuild costs the base limit does not contemplate.

After a partial loss, the village may require sprinkler, electrical, or accessibility upgrades — including demolition of undamaged portions. coverage is how you pay that increment. Older Illinois masonry buildings live on this .

Peak season / seasonal contents

Endorsement

A higher contents limit for the months stock actually peaks.

A warehouse that fills in Q4 should not carry a January inventory limit all year. Peak-season raise business personal property for stated months. Underinsuring stock is a problem on contents, not only on the building.

Sewer backup

Endorsement

Water that comes up through drains — not flood.

Sewer and drain backup is an . Flood from a rising body of water is typically excluded and may need a separate policy. Chicagoland warehouses on slabs still take water from drains after a storm. Do not treat them as one coverage.

Spoilage

Endorsement

Stock that dies when refrigeration or power fails.

If you store temperature-sensitive inventory, spoilage is a contents conversation — not a building fire claim. The sets a limit and often requires working refrigeration maintenance. Pair it with equipment breakdown and off-premises power.

Utility services

Endorsement

Income when the outage starts off your property.

A neighborhood outage or a damaged off-premises line can shut a plant without damaging your building. Utility-services extend business income (and sometimes extra expense) to that fact pattern. The unendorsed form often stops at the property line.

Ready for a Quote?

Speak with a local advisor who understands your coverage needs.

  • Geico insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • AAA insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Hartford insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Progressive insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Liberty Mutual insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Travelers insurance quotes through Hausman-Kunkel Insurance in Roselle, IL
  • Safeco insurance quotes through Hausman-Kunkel Insurance in Roselle, IL

Contact Hausman-Kunkel Insurance

As an independent agency, we are here to help you find the right coverage.

Please do not include sensitive, private information in this area.

Get a Quote

It only takes a minute to get started.

  • Fill out the form, we'll be in touch.
  • Go over your options with an agent.
  • Get the coverage you need.

Would you rather discuss this in person? Get in touch with an agent today!

Contact Us